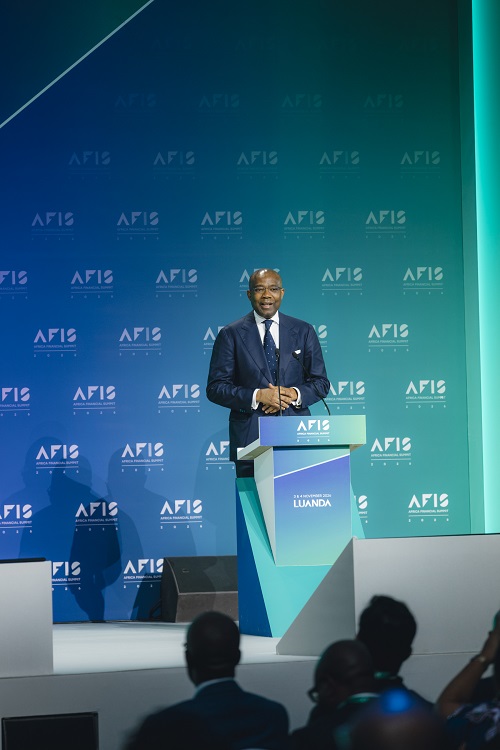
Mr. Aigboje Aig-Imoukhuede, Chairman Access Holdings Plc
…Access Holdings Chairman calls for stronger African banks, integrated financial markets, and a fundamental shift towards making capital work for the continent’s prosperity.
Chairman of Access Holdings Plc, Aigboje Aig-Imoukhuede, has challenged African central banks, financial institutions, and policymakers to move beyond preserving financial stability and focus on translating the continent’s capital into productivity, economic growth, and shared prosperity.
Speaking at the closing session of the Africa Financial Summit (AFIS) 2026 in Luanda, Angola, Aig-Imoukhuede argued that Africa’s next phase of economic development would depend less on the volume of capital available and more on how effectively that capital is mobilised and deployed.
“The real question is: Are we making the capital we have count?” he asked.
Reflecting the summit’s theme, Making Capital Count: Unlocking Growth Through African Finance, he challenged participants to reconsider how financial institutions can unlock Africa’s economic potential.
Aig-Imoukhuede acknowledged African central banks’ progress in strengthening monetary stability, banking supervision, and financial resilience.
Several economies had achieved macroeconomic stability, he noted, but its impact would remain limited unless it translated into productive investment and improved living standards.
“A banking system can be well, can be as safe as you want it to be, it can be profitable, but then it can still serve an economy that is very underperforming,” he said.
According to him, the success of Africa’s financial systems must increasingly be measured not only by inflation, financial stability, and institutional profitability, but also by their contribution to lifting people out of poverty and expanding economic opportunity.
Unlocking Capital Trapped in African Businesses
A central theme was the need to release liquidity trapped in commercial transactions involving small and medium-sized enterprises.
He observed that millions of African businesses create value but struggle to access working capital to sustain and expand operations.
He argued that businesses supplying goods and services to creditworthy corporate customers should be able to obtain financing against those transactions at rates reflecting the credit standing of their buyers.
“When an SME supplies goods to a creditworthy buyer, that SME should be able to attract capital and financing at the same cost of the credit rating of that buyer immediately,” he said.
Drawing attention to developments in India and Brazil, where digital invoicing systems have supported more efficient commercial financing, he challenged African regulators and financial institutions to develop similar infrastructure.
This could improve entrepreneurs’ access to finance, strengthen supply-chain liquidity, and unlock productive capacity constrained by inefficient payment systems.
He also called for greater mobilisation of long-term domestic savings into infrastructure and real-sector investments.
“We can’t use bank deposits, which can be withdrawn tomorrow, to finance long-term projects which require 20-year money,” he observed.
Citing the Dangote Refinery as evidence of investors’ appetite, he urged Africa to connect household savings, pension assets, and institutional capital to long-term opportunities.
Aig-Imoukhuede further warned that excessive government borrowing could constrain private-sector access to finance, calling for stronger coordination between monetary and fiscal authorities.
He suggested that future AFIS discussions should bring finance and budget ministers together with central bank governors to address the structural challenges limiting productive investment.
African Banks Must Translate Scale into Global Competitiveness
Turning to the banking industry, Aig-Imoukhuede challenged African financial institutions to ensure that their growing continental presence delivers economic value.
He acknowledged opportunities created as international banks reduce their exposure and indigenous institutions fill the gaps.
However, he cautioned that replacing foreign ownership with African ownership should not, in itself, be considered sufficient progress.
“We must translate the scale we are building into globally competitive value,” he declared.
African banks, he argued, need the international reach and infrastructure to serve businesses as effectively as the multinational institutions they are replacing.
Using Access Bank’s operations in Angola as an example, he explained that the Group’s ambition extends beyond becoming a domestic banking institution.
“We haven’t come to Angola to serve you simply as a strong domestic Angolan bank, we want to serve you as a stronger and better international bank than those who have left,” he said.
He emphasised the importance of African banks establishing meaningful connections with international financial centres, developing clearing capabilities, and investing in payment infrastructure that enables African businesses to participate efficiently in global commerce.
Drawing comparisons with the evolution of Asian banking institutions, particularly in China, he argued that Africa’s financial institutions must develop the capacity to connect domestic economies with international markets while supporting deeper regional integration.
His remarks underscored a broader shift in the African banking narrative: from geographic expansion and institutional scale to competitiveness, connectivity, and measurable economic value.
Integration Must Come Before a Common African Currency
Aig-Imoukhuede also called for faster economic and financial integration, arguing that fragmented markets constrain Africa’s ability to mobilise capital and grow.
He cautioned against allowing discussions about a common African currency to overshadow the more immediate task of integrating markets, financial infrastructure and the movement of goods, services, and people.
“Integration must precede monetary union,” he said.
Illustrating the practical barriers confronting African integration, he recounted how his chief of staff had been unable to accompany him to Angola because of visa difficulties.
He questioned how the continent could aspire to develop integrated financial markets while maintaining restrictions that complicate the movement of people conducting legitimate business across African borders.
According to him, meaningful financial integration requires a coordinated effort to improve cross-border payments, establish interoperable financial systems, deepen capital markets, and create conditions that allow African businesses and investors to operate across national boundaries.
He outlined three priorities for central banks and policymakers: building interoperable financial infrastructure, developing integrated African financial markets, and pursuing greater macroeconomic convergence.
These reforms, he argued, would enable capital to flow more efficiently across borders, broaden investment opportunities, and strengthen the continent’s collective economic resilience.
He also stressed that integration requires more than technical reforms or regulatory agreements. It demands a genuine commitment among African leaders and institutions to the idea of a more connected and prosperous continent.
Making Capital Count Over the Next Two Decades
Looking ahead, Aig-Imoukhuede challenged Africa’s financial leaders to consider what meaningful progress should look like over the next 10 to 20 years.
He questioned whether African businesses would be able to raise capital more efficiently across borders, whether pension funds would increasingly finance infrastructure rather than concentrate on government securities, and whether financial institutions would succeed in translating the continent’s resources into broader prosperity.
“Will we make capital count?” he asked.
Despite the challenges, he expressed confidence that collaboration among governments, regulators, financial institutions, and private-sector leaders would advance Africa’s development.
For Access Holdings, his message reinforces the importance of translating the Group’s expanding African footprint into sustainable economic value through stronger financial connectivity, productivity and solutions that enable businesses and communities to grow.
Ultimately, Aig-Imoukhuede’s address challenged Africa’s financial industry: the next measure of success will not simply be how much capital the continent attracts, how stable its banks become, or how extensively its financial institutions expand.
It will be how effectively Africa converts its financial resources into productive enterprise, integrated markets, and lasting shared prosperity for its people.
Comment here